Solar Energy UK just told the government it won’t even try to build solar panels in Britain.
And that might be the smartest industrial policy decision I’ve seen in years.
Their roadmap targets £5 billion in economic contribution by 2035, nearly triple the current £1.9 billion. Ten policy recommendations. Hundreds of pages of analysis. But the core admission is stark: the UK won’t compete in solar module manufacturing.
This isn’t surrender. It’s the kind of strategic clarity that separates effective policy from expensive failure.
When Energy Security Meets Economic Reality
I’ve been watching energy markets convulse from geopolitical shocks. U.S. jet fuel prices nearly doubled in recent weeks, jumping from roughly $2.50 to $4.90 per gallon. Against that backdrop, the UK is making a calculated bet on which parts of the solar supply chain actually matter for domestic security.
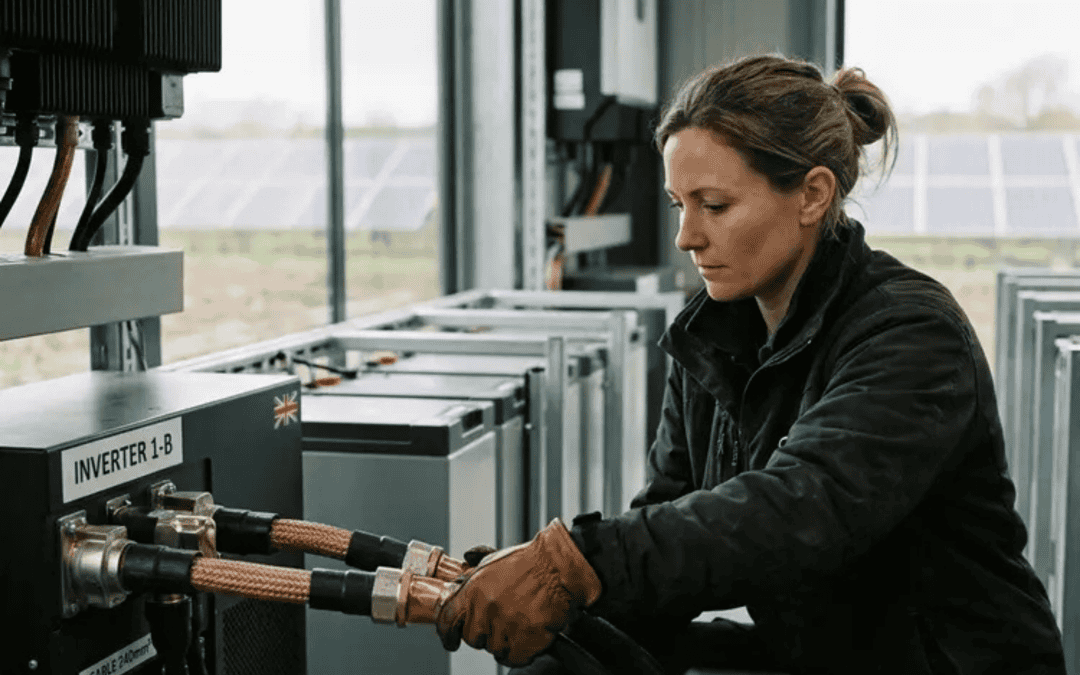
Chris Hewett, chief executive of Solar Energy UK and member of the government’s Solar Taskforce, launched these recommendations in parliament with energy minister Michael Shanks present. The proposal focuses on cables, batteries, inverters, and supporting structures, components where the UK can compete.
Solar Energy UK acknowledges that module manufacturing is “too expensive to develop and scale in the UK to be competitive with global markets.” This isn’t pessimism. It’s strategic realism.
Building What Doesn’t Exist
The economic projections show employment quality, not just quantity. The solar and storage sectors already generate an average of nearly £90,000 in gross value added per employee, 40% higher than the UK national average.
Employment is expected to more than double from 20,000 to over 40,000 jobs by 2035. The real value isn’t in the headcount. It’s in what those jobs represent: high-productivity positions in manufacturing, installation, and maintenance that can’t be offshored.
The ten policy recommendations form an ecosystem rather than a checklist:
1. Long-term project pipeline clarity: Manufacturers need visibility beyond 2030 to justify capital-intensive operations
2. Domestic capability assessment: Creating a database of what already exists in the UK supply chain
3. Strategic investment coordination: Great British Energy’s £1 billion allocation to renewable supply chains
4. Testing and validation facilities: Infrastructure to bridge the gap between laboratory innovation and commercial deployment
5. Technical Excellence Colleges: Workforce development that precedes rather than follows industry scaling
6. Fair contracting practices: Project bank accounts to stabilize smaller suppliers
7. Local content prioritization: Encouraging domestic sourcing without triggering trade violations
8. Office for Solar and Storage: Centralized coordination for fragmented policy initiatives
9. Innovation commercialization support: Targeted funding for the “valley of death” between R&D and market
10. Grid connection acceleration: Addressing the infrastructure bottleneck blocking deployment
The Grid Connection Crisis
Solar Energy UK identified more than 40 projects and 3.5GW of capacity blocked by grid connection problems. That’s at least £1.37 billion in capital investment sitting idle.
Developers report timescales of 12 to 18 months, sometimes 2 years, just to receive impact assessments. The standard should be 3 to 6 months.
The best supply chain policy in the world doesn’t matter if you can’t connect projects to the grid. This mundane bottleneck kills ambitious targets.
What Great British Energy Actually Does
The government’s £1 billion commitment through Great British Energy’s “Energy Engineered in the UK” programme represents a different approach to industrial policy.
The initial £300 million targets offshore wind and networks, focusing on urgent bottlenecks in blades, turbines, transmission cables, and converter stations. Another £700 million follows for floating offshore platforms, electric cables, and hydrogen infrastructure.
This isn’t the government directly operating factories or pure market-based development. It’s a hybrid model where a government-backed entity operates at the intersection of public and private sectors, taking positions too risky for private capital but too commercially oriented for traditional government programs.
The model addresses a specific market failure: the temporal mismatch between electoral cycles and industrial development timelines. Politicians operate on 2 to 5-year horizons. Manufacturing facilities require 10 to 20-year commitment horizons.
Great British Energy provides the long-term capital patient enough to bridge that gap.
The Innovation Problem Isn’t Innovation
The UK has world-class research capabilities. It has a growing market demand. What it lacks is the infrastructure to commercialize innovations at scale.
This is the “valley of death” between laboratory success and market deployment. You can prove a technology works in controlled conditions. Scaling it to industrial production is a different challenge entirely.
The policy recommendations emphasize dedicated testing facilities and industrial research funding specifically for this transition phase. The constraint isn’t discovery. It’s deployment.
Raw innovation capacity often exceeds commercialization capacity. Funding allocation should shift from discovery-focused research toward deployment-focused development.
The Rural Economics Wildcard
Here’s a data point that surprised me: Payments to farmers hosting solar installations reached £61 million in 2024. By 2035, that number is projected to exceed £300 million, 7% of the total income that English farms received in 2023.
This isn’t a footnote. It’s a structural shift in rural economics.
Solar installations provide income diversification that helps farmers remain financially viable while contributing to renewable energy goals. The land remains agricultural. The economy becomes sustainable.
Domestic supply chains need domestic deployment sites. Farmers provide that. And unlike most industrial policy mechanics, this one pays for itself while keeping land in agricultural use.
The Information Problem
One of the ten recommendations is simple: create a database of domestic capabilities, components, and services.
Information asymmetry is a major supply chain constraint. In complex, fragmented markets, knowing what exists domestically may be as important as creating new capabilities.
If procurement managers don’t know a UK supplier exists, they default to established international sources. If investors don’t know what gaps exist, they can’t target opportunities. If policymakers don’t know what capabilities are present, they can’t design effective support mechanisms.
Supply chain transparency enables the coordination that turns fragmented capabilities into functional ecosystems.
The Workforce Timing Problem
Technical Excellence Colleges with specific objectives for solar and storage sectors address a temporal challenge: skills training must begin before mass deployment.
Traditional economic models assume workforce development follows demand. You create jobs, then people train for them. But in rapidly scaling industries with specialized technical requirements, that creates bottlenecks.
Labor shortages constrain growth even when capital and demand are present. You need electricians who understand solar installations. Engineers who can maintain battery systems. Technicians who can troubleshoot inverters.
The workforce isn’t a resource that appears when needed. It’s a constraint that must be addressed proactively.
What This Reveals About Globalization’s Limits
The recognition that the UK can’t compete in module manufacturing signals something larger than solar policy.
For decades, global specialization suggested that advanced economies should focus on high-value services and innovation while outsourcing manufacturing to lower-cost regions. This maximized efficiency.
But efficiency and resilience are different objectives. The IMF’s 2026 report highlights how the disruption of 33% of global seaborne fertilizer trade sparked fears of a food security crisis, part of a broader “geopolitical fragmentation” where economic efficiency is increasingly sacrificed for national security and supply chain resilience.
The shift from “just in time” to “just in case” logistics is becoming permanent. When advanced economies determine they can’t compete in manufacturing even for strategic technologies, it raises questions about extreme global specialization.
The UK’s solar policy isn’t abandoning globalization. It’s recalibrating toward regional self-sufficiency in critical components while accepting global integration where it makes sense.
The Policy Design Challenge Nobody Solves
Democratic governance operates on short cycles while industrial development requires long commitments.
The Clean Power by 2030 target is ambitious. But Solar Energy UK points out it’s “relatively short-term” for manufacturers considering capital-intensive operations.
Electoral cycles and ministerial tenures operate on 2 to 5-year horizons. Building a manufacturing facility, training a workforce, establishing supply relationships, and achieving profitable scale takes 10 to 20 years.
This temporal mismatch is a fundamental challenge for any capital-intensive industrial policy in democratic systems. You need policy stability that outlasts individual governments.
The UK’s approach, embedding recommendations in parliamentary processes, securing ministerial endorsement, and building on existing frameworks like the Solar Roadmap, attempts to create institutional momentum that survives political transitions.
Whether it works remains to be seen.
What Actually Happens Next
The recommendations sit in front of policymakers now. Great British Energy has £1 billion allocated. The Solar Taskforce has ministerial access. The economic projections create measurable targets.
Policy documents don’t build supply chains. Deployment does.
The real test isn’t adoption. Its execution. Training programs launching before demand peaks. Testing facilities validating innovations. Databases make domestic capabilities visible. Contracting practices stabilizing smaller suppliers.
I’m watching to see if this survives contact with reality. Most industrial policy dies quietly when political priorities shift or implementation proves harder than planning. But this framework has something most don’t: acknowledgment of what won’t work before committing resources to what might.