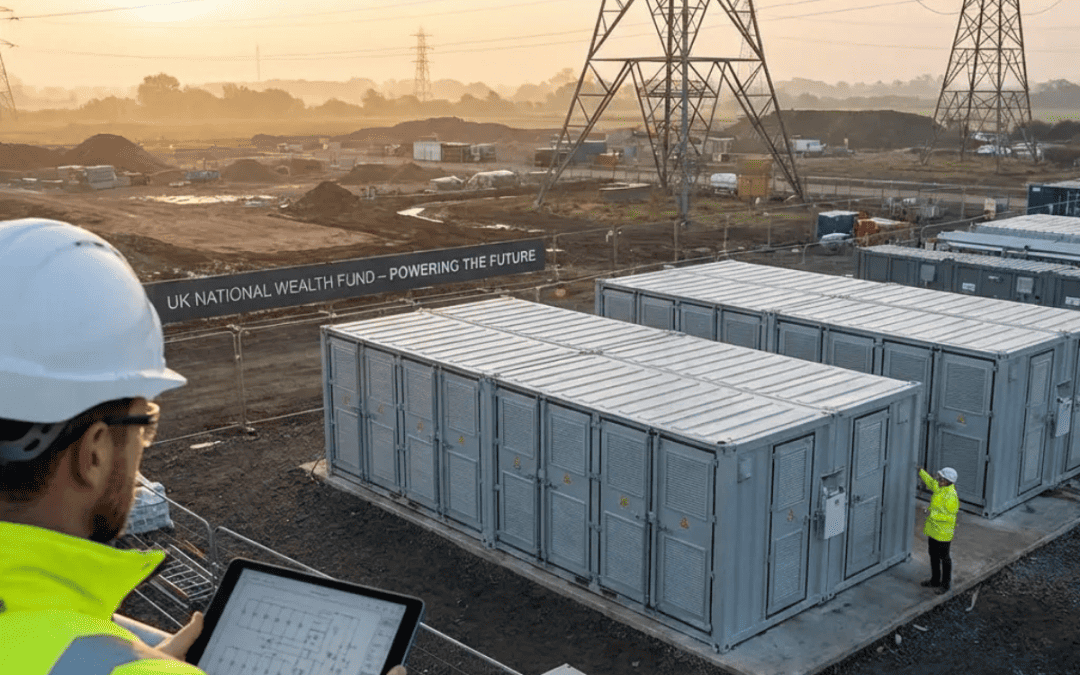
The UK’s National Wealth Fund has £27.8 billion in total public capital, with £19.4 billion remaining to deploy over the next five years. The fund targets mobilizing over £100 billion in total investment through private partnerships. For context, the US EPA’s Greenhouse Gas Reduction Fund achieved 7:1 leverage, and Connecticut’s Green Bank hit 6:1. The NWF’s long-term target mobilization ratio of 1:3 is more conservative than international green bank models, reflecting cautious risk assumptions about the UK market’s ability to absorb rapid capital deployment.
Capital Deployment Priorities
The NWF has already committed one-third of its capital. That’s £4.5 billion across more than 30 investments since relaunch, mobilizing over £17 billion in private investment.
The fund has tripled its pace of deployment, earmarking £5.8 billion specifically for five subsectors: ports and supply chains, carbon capture, hydrogen, battery manufacturing, and steel. The government considers these sectors investment-ready, distinguishing them from aspirational climate technologies still seeking commercial viability.
The rest of the capital spreads across ten priority sectors including energy storage, power grids, and nuclear power. The £5.8 billion concentration signals where officials see the highest multiplier effects for supply chain development—investments that don’t just decarbonize but rebuild domestic manufacturing capacity.
Ports get direct support because they’re infrastructure chokepoints. Offshore wind at scale requires port capacity. The £55 million committed to specific ports unlocks the supply chain for downstream development.
Battery manufacturing and steel get priority because the UK wants to capture value domestically rather than importing finished products. This is industrial policy dressed up as climate policy.
Battery Storage Expansion
The government’s Clean Power 2030 Action Plan projects the UK will need 23-27 GW of battery storage by 2030—up from approximately 7 GW operational today. This roughly fourfold increase in five years represents one of the most aggressive storage buildouts globally.
The NWF backed the Thorpe Marsh project, which will deliver 1,400 MW of capacity by mid-2027—three times larger than any other battery energy storage system currently operating or under construction in the UK. This scale matters because battery storage economics improve dramatically with size, reducing per-unit costs while increasing grid flexibility.
By 2050, the UK could need up to 51 GW of storage capacity. The gap between current infrastructure and future requirements creates significant capital deployment opportunities—and a first-mover advantage for companies that can execute at scale. The market structure favors consolidation: large players with access to capital and proven execution track records will win the most lucrative contracts, while smaller developers face increasing pressure to partner or exit.
Grid Infrastructure Bottlenecks
The UK needs an estimated £58 billion in grid investment by 2035, with Transmission Owner business plans for the next five-year price control period proposing over £60 billion in investment. This represents the largest grid modernization effort since the 1960s nationalization.
Officials describe this as transforming the electricity network at a scale and pace not seen since the 1960s. Without transmission capacity, renewable generation capacity is ineffective.
The NWF’s focus on debt and guarantee financing for grid investments reflects a recognition that transmission infrastructure operates on different economics than generation assets. These are mature, regulated utilities with predictable cash flows that don’t need venture capital—they need optimized capital structures that reduce the cost of capital. Every basis point reduction in financing costs compounds across decades of asset life, potentially saving billions.
The constraint is financing structure and regulatory frameworks, not technology. The NWF emphasizes guarantees to de-risk projects so private capital flows in at commercial rates. This approach recognizes that the UK’s pension funds and infrastructure investors sit on trillions in assets seeking stable, long-term returns. The challenge isn’t finding capital—it’s structuring opportunities that meet institutional investment criteria.
Corporate PPAs for Large-Scale Solar
Companies like Tesco and Amazon now source up to 75% of their energy through solar power purchase agreements. Solar offtakers experienced 25% growth from December 2021 to December 2024, adding 3 GW of capacity. The Clean Power Action Plan targets up to 47 GW by 2030, requiring a dramatic acceleration in corporate PPA adoption.
When corporations sign long-term PPAs, they provide revenue certainty that makes projects bankable. Developers can secure debt financing against contracted cash flows, fundamentally changing the risk profile from merchant exposure to counterparty credit risk. The PPA model turns electricity from a commodity into a contracted service, which institutional investors understand and price efficiently.
For the NWF, this means prioritizing large-scale projects that can serve corporate offtakers. The fund isn’t backing residential solar or small commercial installations. They’re targeting utility-scale projects with creditworthy counterparties and long-term contracts.
This aligns with sovereign wealth-style risk-return profiles. Predictable cash flows, inflation-linked revenues, and investment-grade counterparties.
Job Creation and Political Imperatives
The government projects over 200,000 jobs created or supported through the NWF’s investments. The fund has already supported more than 70,000 jobs across its initial deployments.
These numbers aren’t incidental. They’re central to maintaining political support for the program.
The emphasis on “place-based regeneration” signals that clean energy transition is being used to address regional economic disparities. This isn’t just about decarbonization—it’s about delivering tangible employment benefits to communities that need economic revitalization. Former industrial regions with existing skilled workforces and underutilized infrastructure become prime targets for battery manufacturing and steel decarbonization investments.
The political sustainability of climate policy depends on visible job creation, which explains why the NWF prioritizes manufacturing and supply chain investments over pure generation assets. A solar farm creates construction jobs temporarily; a battery manufacturing facility creates permanent employment with export potential. This calculation drives sectoral allocation more than carbon reduction per pound invested.
The fund’s strategic plan acknowledges this explicitly. The sectoral prioritization reflects both technical requirements for decarbonization and political requirements for maintaining public support.
Carbon Impact
The NWF projects its investments will save an estimated 500 million tonnes of CO2 equivalent by 2050—the quantifiable environmental return on public capital deployment that justifies the entire program to climate-focused stakeholders.
The five-year deployment window creates urgency. The 2050 carbon impact provides long-term legitimacy. The structure balances immediate action with generational outcomes. The carbon accounting turns public investment into measurable environmental returns.
For private investors, this creates regulatory certainty. The government committed capital and established clear sectoral priorities. That reduces policy risk, which is often the largest barrier to infrastructure investment.
Capital Allocation Principles
The NWF’s structure reveals three core investment principles. First, the fund operates independently within the Treasury but maintains government backing—a hybrid structure that provides flexibility while maintaining credibility. Private investors know the government stands behind the commitments, reducing perceived policy risk.
Second, the tiered framework prioritizes sectors by investment readiness. The ten key sectors get first access to capital. The 15 strategic investment sectors come next. This hierarchy prevents capital from chasing marginal opportunities while proven investments lack funding.
Third, the emphasis on guarantees and debt financing over equity investments signals a focus on capital efficiency. The fund wants to mobilize the maximum private capital per pound of public investment, recognizing that public capital is the scarcest resource in the equation.
The goal is to maximize total investment mobilized, not returns on public capital. A project that generates moderate returns but mobilizes significant private capital achieves the policy objective better than a high-return project that requires mostly public funding. This distinction separates sovereign development finance from traditional investment management.
International Context
The NWF’s conservative 5:1 leverage ratio compared to US and other international models suggests either more cautious risk assumptions or recognition of UK-specific constraints—perhaps limited pipeline depth, regulatory uncertainties around planning approvals, or concern about crowding out private capital in an already active market.
The scale of the program reflects awareness of global capital mobility. Clean energy capital flows to markets with the most attractive risk-adjusted returns, regulatory stability, and execution certainty. If the UK doesn’t create competitive investment frameworks, capital simply deploys elsewhere.
The technology-agnostic approach—including nuclear power alongside renewables—signals pragmatism over ideology. The government prioritizes decarbonization outcomes over specific technology pathways, recognizing that different technologies serve different roles in a balanced energy system. Countries that create attractive risk-adjusted returns will capture disproportionate investment. The NWF represents the UK’s bid to position itself as a preferred destination for clean energy capital amid fierce competition from the US Inflation Reduction Act, EU Green Deal Industrial Plan, and China’s manufacturing dominance.
Strategic Bets on Emerging Technologies
The hydrogen and long-duration energy storage prioritization reveals a bet on emerging technologies where the UK could establish early leadership. These aren’t the safest investments—they’re strategic positioning for future markets where first-movers can capture intellectual property, manufacturing expertise, and export opportunities.
The specific equity consideration for LDES Cap and Floor projects indicates the government recognizes these technologies need different financial structures than mature renewables. Early-stage technologies require patient capital willing to accept lower initial returns for higher upside potential, while mature technologies optimize for cost of capital.
The ports and supply chain allocation reflects understanding that infrastructure constraints can bottleneck entire industries. Without adequate port facilities for turbine assembly and deployment, offshore wind cannot scale regardless of available capital for generation assets.
The most important investments often enable other investments rather than generating direct returns. Financial analysis that focuses on individual project returns rather than system-level enablement misses this dynamic.
Execution Speed
The NWF tripled its deployment pace—an acceleration that matters more than the absolute capital committed. In infrastructure investment, momentum creates momentum.
The five-year deployment window creates accountability with clear success metrics. Either the fund hits its targets or it doesn’t. The timeline is short enough to maintain urgency and political relevance but long enough to execute complex infrastructure projects that require multi-year development cycles.
The early successes with battery storage and grid investments build credibility for the larger £100 billion ambition. Each completed project demonstrates the model works.
Momentum matters in infrastructure investment. Projects that close attract follow-on investment. Developers that successfully navigate the NWF process can replicate the model across multiple assets. Success compounds.
The UK is running a large-scale experiment in blended finance for clean energy infrastructure. Other countries are watching closely. If the NWF achieves its £100 billion mobilization target while delivering measurable carbon reductions and job creation, it establishes a replicable model for sovereign climate finance. If it falls short, it provides expensive lessons about the limits of public capital leverage in mature economies.
The next five years will determine whether the UK positions itself as a clean energy capital leader or simply another market chasing global investment that flows elsewhere. The structure is clear. The capital is committed. The sectoral priorities are established. Execution is the only variable that matters now.